How Much Does It Really Cost to Insure a Maserati Ghibli
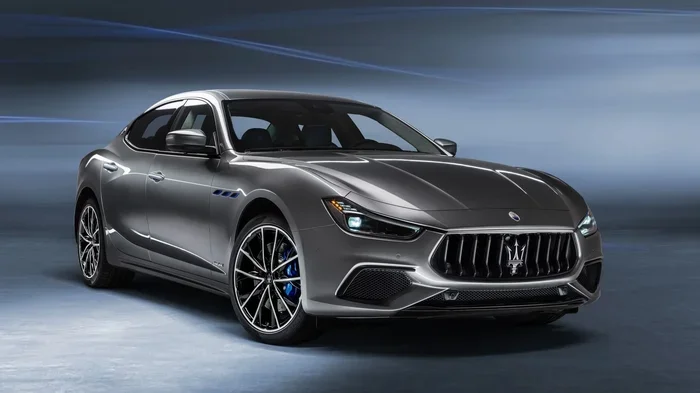
Insuring a Maserati Ghibli typically costs between $2,000 and $5,000 per year, depending on your location, driving history, and coverage level. Luxury car insurance for this Italian sedan runs higher than average due to expensive parts, repair costs, and theft risk. Understanding what drives these rates helps you find the best policy without overpaying.
Owning a Maserati Ghibli is a dream for many car enthusiasts. That sleek Italian design and powerful engine turn heads everywhere you go. But there is a less glamorous side to luxury car ownership: insurance. If you are thinking about buying a Ghibli or already own one, you need to understand what Maserati Ghibli insurance cost really looks like.
The truth is, insuring a luxury vehicle is not the same as insuring a regular sedan. Premium cars come with premium price tags, and that extends to your insurance policy. In this guide, we break down everything you need to know about the cost to insure a Maserati Ghibli. We will cover the factors that influence your rate, the types of coverage available, and practical tips to help you save money.
Let us dive in.
Key Takeaways
- Average annual premium: Maserati Ghibli insurance ranges from $2,000 to $5,000 per year based on multiple factors.
- Luxury vehicles cost more to insure: High repair costs, expensive parts, and theft risk drive up premiums for Italian sedans.
- Your personal profile matters: Age, driving record, credit score, and location all influence your exact rate.
- Coverage levels vary: Full coverage with comprehensive and collision costs significantly more than liability-only policies.
- You can save money: Bundling policies, increasing deductibles, and maintaining a clean driving record help lower costs.
- Compare quotes: Shopping around among multiple insurers is the single best way to find affordable coverage for a Ghibli.
- Model year and trim affect rates: Newer and higher-performance Ghibli trims typically carry higher insurance premiums.
📑 Table of Contents
- Why Maserati Ghibli Insurance Costs More Than Average
- Factors That Determine Your Maserati Ghibli Insurance Rate
- Coverage Types for a Maserati Ghibli
- Average Cost Estimates for Maserati Ghibli Insurance
- Tips to Lower Your Maserati Ghibli Insurance Cost
- Common Mistakes Ghibli Owners Make with Insurance
- How to Get the Best Maserati Ghibli Insurance Quote
- Final Thoughts on Maserati Ghibli Insurance
Why Maserati Ghibli Insurance Costs More Than Average
Insurance companies base their rates on risk. The more likely a car is to be involved in an accident, stolen, or expensive to repair, the higher the premium. The Ghibli checks all three boxes, which is why luxury car insurance for this model runs higher than most vehicles on the road.
Expensive Parts and Repairs
A Maserati is not a Toyota. When something breaks, the repair costs can be staggering. Original manufacturer parts for a Ghibli cost significantly more than parts for mainstream vehicles. Even a minor fender bender can result in a repair bill that totals thousands of dollars. Insurance companies factor this into your premium because they know they will likely pay out more in claims.
For example, a simple windshield replacement on a Ghibli can cost well over $1,000. Compare that to a standard sedan where the same job might run $300 to $500. These differences add up quickly and directly impact your Maserati insurance premium.
Theft Risk
Luxury Italian sedans are prime targets for car thieves. The Ghibli, with its high resale value and desirability, faces a greater theft risk than average vehicles. Insurance providers account for this risk by charging higher comprehensive coverage rates. If you park your Ghibli on the street overnight, your rates could be even higher than if you garage it.
Performance and Speed
The Ghibli is a performance sedan. It accelerates fast and handles like a sports car. Insurance companies associate high-performance vehicles with a greater likelihood of accidents. Speeding tickets and reckless driving claims are more common among luxury sports sedan owners, which drives up the overall risk profile for this vehicle category.
Factors That Determine Your Maserati Ghibli Insurance Rate
No two Ghibli owners pay the same insurance rate. Several personal and vehicle-specific factors determine your exact premium. Understanding these factors helps you anticipate what you will pay and find ways to reduce costs.
Your Age and Driving Experience
Younger drivers pay significantly more for insurance across all vehicle types. For a luxury car like the Ghibli, the difference is even more pronounced. A 20-year-old driver might pay double what a 40-year-old driver pays for the same coverage. This is because statistics show that younger, less experienced drivers are more likely to file claims.
If you are a teenager or young adult, you might want to check whether a 17-year-old can get car insurance in their name and what the associated costs look like for a luxury vehicle. Age restrictions and eligibility requirements vary by state, but the general trend is clear: more driving experience equals lower rates.
Your Driving Record
A clean driving record is your best friend when it comes to insurance rates. Traffic violations, accidents, and DUI convictions all signal higher risk to insurers. Even a single speeding ticket can increase your premium by 20 to 30 percent. For a Ghibli owner, maintaining a spotless driving record is essential to keeping insurance costs manageable.
Your Location
Where you live and park your car matters a great deal. Urban areas with high traffic density and crime rates typically have higher insurance premiums. If you live in a city like New York, Los Angeles, or Miami, expect to pay more than someone living in a rural area. Your zip code is one of the first things an insurer checks when generating a quote.
Your Credit Score
In most states, insurance companies use your credit score as a factor in determining your rate. A higher credit score generally leads to lower premiums. This practice, known as credit-based insurance scoring, is controversial but widely used. Maintaining good credit can save you hundreds of dollars per year on your Ghibli insurance.
Ghibli Model Year and Trim Level
Not all Ghiblis are created equal when it comes to insurance costs. A 2017 base model will cost less to insure than a 2023 Ghibli Trofeo with its powerful V6 engine. Newer models also cost more because replacement parts are pricier and the vehicle has a higher market value. When shopping for a Ghibli, consider how the model year and trim level will affect your long-term insurance expenses.
Coverage Types for a Maserati Ghibli
Understanding the different types of car insurance coverage helps you make informed decisions about your policy. Here is a breakdown of the main coverage options available for a Ghibli owner.
Liability Coverage
Liability coverage is the most basic and legally required form of insurance in most states. It pays for damages and injuries you cause to others in an accident. For a Ghibli, liability-only coverage is the cheapest option, but it does not protect your own vehicle. If you scratch your Ghibli in a parking lot, liability coverage will not help you pay for repairs.
Collision Coverage
Collision coverage pays for damage to your own vehicle after an accident, regardless of who is at fault. For a luxury car like the Ghibli, collision coverage is essential but adds significantly to your premium. The deductible, which is the amount you pay out of pocket before insurance kicks in, typically ranges from $500 to $1,000 for collision coverage on luxury vehicles.
Comprehensive Coverage
Comprehensive coverage protects against non-accident damage, including theft, vandalism, fire, flooding, and falling objects. Given the theft risk associated with luxury Italian sedans, comprehensive coverage is highly recommended for Ghibli owners. This coverage also includes windshield damage, which is particularly relevant for a low-slung sports sedan where the windshield is vulnerable to road debris.
Uninsured and Underinsured Motorist Coverage
This coverage protects you if you are in an accident with a driver who has no insurance or insufficient coverage. It is an affordable add-on that provides valuable peace of mind, especially in areas with high rates of uninsured drivers.
Average Cost Estimates for Maserati Ghibli Insurance
While exact rates vary widely based on the factors discussed above, here are some general estimates to give you a sense of what to expect.
Annual Premium Ranges
On average, Ghibli owners pay between $2,000 and $5,000 per year for full coverage insurance. The wide range reflects the many variables that insurers consider. A middle-of-the-road estimate for a typical Ghibli owner with a clean record living in a moderate-risk area falls around $3,000 to $3,500 annually.
For comparison, the average American pays about $1,500 to $2,000 per year for standard sedan insurance. So insuring a Ghibli can cost nearly double the national average. This premium reflects the real cost of owning and operating a luxury performance vehicle.
Monthly Payment Breakdown
Breaking down the annual cost into monthly payments makes the expense more manageable to understand. At the average rate of $3,200 per year, you would pay roughly $265 to $280 per month. Full coverage with low deductibles pushes this higher, while liability-only coverage brings it down significantly.
| Coverage Type | Estimated Annual Cost | Estimated Monthly Cost |
|---|---|---|
| Liability Only | $1,200 – $2,000 | $100 – $167 |
| Full Coverage (Low Deductible) | $3,500 – $5,000 | $292 – $417 |
| Full Coverage (High Deductible) | $2,500 – $3,500 | $208 – $292 |
| Luxury Add-Ons (Roadside, Gap, etc.) | $300 – $600 | $25 – $50 |
Tips to Lower Your Maserati Ghibli Insurance Cost
Paying thousands of dollars a year for insurance stings, but there are proven strategies to reduce your premium without sacrificing coverage. Here are practical tips that Ghibli owners can use to save money.
Shop Around and Compare Quotes
The single most effective way to find affordable insurance is to compare quotes from multiple providers. Each insurer uses different algorithms and pricing models, so rates can vary by hundreds or even thousands of dollars for the same driver and vehicle. Do not settle for the first quote you receive. Get at least three to five quotes before making a decision.
Bundle Your Insurance Policies
If you also have homeowners or renters insurance, bundling them with your auto policy can unlock significant discounts. Many insurers offer 10 to 25 percent savings when you combine multiple policies. This is an easy way to reduce your overall insurance expenses.
Increase Your Deductibles
Raising your deductible from $500 to $1,000 or even $2,000 can lower your monthly premium considerably. The trade-off is that you will pay more out of pocket if you file a claim. For safe drivers who rarely get into accidents, this is a smart strategy to reduce ongoing costs.
Maintain a Clean Driving Record
As mentioned earlier, your driving record has a major impact on your rates. Avoiding traffic violations and accidents keeps your premium low. Consider taking a defensive driving course, which some insurers offer discounts for. Even completing a safe driving program can shave a few dollars off your annual premium.
Install Anti-Theft and Safety Devices
Equipping your Ghibli with anti-theft devices like GPS tracking, alarm systems, and steering wheel locks can qualify you for insurance discounts. Modern safety features such as automatic emergency braking, lane departure warnings, and blind-spot monitoring also help lower rates. Insurers reward vehicles equipped with technology that reduces accident risk.
Pay Annually Instead of Monthly
Some insurers charge a convenience fee for monthly payments. Paying your premium in full once a year avoids these fees and can save you $50 to $100 annually. It requires a larger upfront payment, but the savings add up over time.
Ask About Loyalty and Affinity Discounts
Many insurers offer discounts for long-term customers, military personnel, educators, and members of certain professional organizations. Always ask your agent about available discounts. You might be eligible for savings you did not even know about.
Common Mistakes Ghibli Owners Make with Insurance
Avoiding common pitfalls can save you money and headaches. Here are mistakes that many luxury car owners make when insuring their vehicles.
Underestimating the True Value of the Vehicle
Some owners insure their Ghibli for its purchase price rather than its actual cash value. As the vehicle depreciates, you may be overpaying for coverage that exceeds the car’s current worth. Review your policy annually and adjust coverage levels as the vehicle loses value.
Choosing the Cheapest Policy
It is tempting to go with the lowest premium, but the cheapest policy often provides inadequate coverage. A Ghibli owner needs robust protection given the high cost of repairs. Make sure your policy covers the full replacement cost or agreed value of the vehicle.
Skipping Comprehensive Coverage
Some owners drop comprehensive coverage to save money. This is a risky move for a luxury vehicle that faces higher theft and vandalism risks. Without comprehensive coverage, you would pay entirely out of pocket for any non-accident damage to your Ghibli.
Not Reviewing Your Policy Regularly
Insurance needs change over time. As your Ghibli ages, you may be able to reduce coverage. Conversely, if you add modifications or accessories, you need to update your policy. Failing to review your coverage annually means you could be paying for unnecessary protection or lacking essential coverage.
How to Get the Best Maserati Ghibli Insurance Quote
Getting the right insurance for your Ghibli starts with a smart shopping process. Here is a step-by-step approach to finding the best policy.
First, gather information about your vehicle, including the model year, trim level, mileage, and any safety features. Next, determine the coverage levels you need based on your financial situation and risk tolerance. Then, request quotes from at least three to five different insurance companies. Compare not just the price but also the coverage limits, deductibles, and customer service reputation.
Consider working with an insurance broker who specializes in luxury vehicles. These professionals understand the unique needs of high-end car owners and can find policies that mainstream agents might overlook. They often have relationships with specialty insurers that cater specifically to luxury and exotic car owners.
Finally, read the fine print before signing any policy. Understand exactly what is covered, what your deductibles are, and what the claims process looks like. A clear understanding of your policy prevents surprises when you need to file a claim.
Final Thoughts on Maserati Ghibli Insurance
Insuring a Maserati Ghibli is a significant ongoing expense that every prospective and current owner should plan for. The cost to insure a Maserati Ghibli runs higher than average due to the vehicle’s luxury status, expensive parts, and performance characteristics. But with the right strategy, you can manage these costs effectively.
Start by understanding the factors that drive your rate. Compare quotes from multiple insurers. Choose coverage levels that match your needs and budget. And take advantage of every discount and savings opportunity available to you. With the right approach, you can protect your Ghibli without breaking the bank.
Owning a luxury car is about more than just the purchase price. It is about the entire ownership experience, and insurance is a key part of that experience. Do your homework, stay informed, and drive confidently knowing you have the right coverage in place.
Frequently Asked Questions
How much does it cost to insure a Maserati Ghibli per month?
On average, monthly insurance for a Ghibli ranges from $165 to $400 depending on your coverage level, deductible, and personal factors. Full coverage with a low deductible will be on the higher end of that range, while liability-only coverage falls on the lower end. Your exact rate depends on your driving record, location, and the insurance company you choose.
Is Maserati Ghibli insurance more expensive than other luxury cars?
Yes, the Ghibli generally costs more to insure than mainstream luxury brands like Lexus or Acura. This is because Maserati parts are more expensive, repair networks are more limited, and the brand has a higher theft risk profile. However, rates vary significantly based on your individual circumstances and the specific model year.
Does the Maserati Ghibli have good safety features that lower insurance costs?
The Ghibli comes equipped with modern safety technology including automatic emergency braking, adaptive cruise control, and blind-spot monitoring. These features can qualify you for insurance discounts with many providers. However, the overall luxury and performance nature of the vehicle still results in higher premiums compared to standard sedans.
Can I insure a used Maserati Ghibli for less money?
Yes, insuring an older Ghibli typically costs less than a new one because the vehicle has depreciated in value. As the market value drops, the cost to insure it decreases proportionally. However, even older Ghiblis cost more to insure than average vehicles due to the ongoing expense of parts and specialized repairs.
What insurance company is best for a Maserati Ghibli?
There is no single best insurer for luxury vehicles. Companies like Hagerty, Hagerty, and Chubb specialize in luxury and exotic car coverage. Mainstream insurers like State Farm, Geico, and Progressive also offer competitive rates. The best approach is to compare quotes from specialty and standard providers to find the right balance of coverage and cost.
Do I need gap insurance for a Maserati Ghibli?
Gap insurance is highly recommended if you are financing or leasing a Ghibli. Luxury vehicles depreciate faster than standard cars, and gap insurance covers the difference between your loan balance and the vehicle’s actual cash value if it is totaled. This protection can save you thousands of dollars in the event of a total loss.