Can I Take a Loan Against My Car and Keep Driving
Yes, you can take a loan against your car and keep driving. A car title loan lets you use your vehicle equity as collateral while you continue to drive. This guide covers how these loans work, requirements, amounts, rates, and tips to get the best deal.
Have you ever found yourself in a tight financial spot and thought about tapping into your car’s value? Maybe you need to cover an emergency bill, pay for home repairs, or handle unexpected medical costs. The good news is that you can get a loan against your car without giving up your wheels. This type of loan is called a car title loan, and it is one of the fastest ways to access cash when you need it most.
In this guide, we will walk you through everything you need to know about getting a loan against your car and keeping it on the road. We will cover how these loans work, what you need to qualify, how much you can borrow, and the pros and cons you should consider. By the end, you will have a clear picture of whether a title loan is the right move for your situation.
Let us dive in and explore the world of vehicle equity loans together. No jargon. No fluff. Just clear, helpful information that you can use right away.
Key Takeaways
- Keep Driving: You can drive your car while repaying the loan in most cases.
- Quick Funding: Many lenders approve and disburse funds within 24 hours.
- Credit Flexibility: Bad credit is often not a barrier since the loan is secured.
- Loan Amount: You can typically borrow between $1,000 and $10,000 based on vehicle value.
- Risk Involved: Defaulting can lead to vehicle repossession.
- Compare Offers: Always shop around for the lowest interest rate and best terms.
📑 Table of Contents
What Is a Loan Against Your Car?
A loan against your car is a type of secured loan where you use your vehicle as collateral. Instead of borrowing money based on your credit score alone, the lender looks at the value of your car. If you own your vehicle outright or have significant equity, you can borrow a portion of that value.
The most common form of this loan is a car title loan. You hand over your vehicle title to the lender as security, but you keep driving your car. Once you repay the loan in full, you get your title back. It is a straightforward process that many people find very appealing.
How Is It Different From a Regular Loan?
A traditional bank loan is usually unsecured. That means there is no collateral backing it up. The lender trusts your credit history and income to repay the money. If you default, they cannot take your car.
A secured loan against your car works differently. Because the lender has a claim on your vehicle, they take on less risk. This often means:
- Faster approval times — sometimes within hours
- Lower credit requirements — great for people with poor credit
- Higher loan amounts — based on vehicle value, not just income
- Shorter repayment terms — usually 12 to 36 months
These differences make auto equity loans a popular choice for people who need quick cash and do not want to wait through a long bank approval process.
How Does a Car Title Loan Work?
Understanding the process helps you feel confident before applying. Here is a step-by-step look at how a car title loan works in practice.
Step 1: Check Your Vehicle Equity
First, figure out how much your car is worth. You can use online tools like Kelley Blue Book or Edmunds to get an estimated vehicle value. Then subtract any remaining balance on your car loan, if you have one. The difference is your vehicle equity.
For example, if your car is worth $15,000 and you still owe $5,000, your equity is $10,000. Most lenders will let you borrow a percentage of that equity, usually between 25% and 50%.
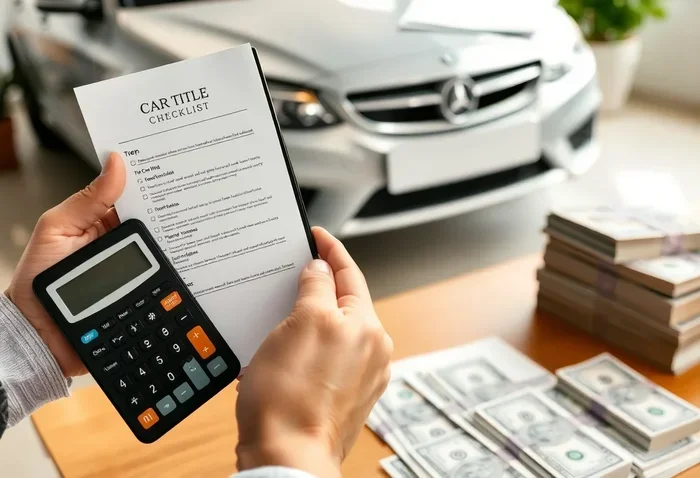
Step 2: Gather Your Documents
You will need a few key documents to apply:
- Vehicle title — free and clear in your name
- Government-issued ID — proof of identity
- Proof of income — pay stubs or bank statements
- Insurance documents — proof of active coverage
- Proof of residence — utility bill or lease agreement
Step 3: Apply and Get Approved
Many lenders offer online applications. You fill out a short form, provide your documents, and get a decision quickly. Some lenders offer same day funding, which is one of the biggest advantages of this loan type.
Step 4: Receive Your Funds and Keep Driving
Once approved, you receive the loan amount, usually via direct deposit. You sign the loan agreement, hand over your title temporarily, and keep driving your car. Simple as that.
Requirements to Get a Loan Against Your Car
The requirements for a title loan are generally less strict than a traditional bank loan. Here is what most lenders look for.
Ownership and Title Status
You must own the vehicle outright or have significant equity. The title should be free and clear, meaning no liens or outstanding loans against it. If you still owe money on your car, some lenders may consider a loan, but the options are more limited.
Vehicle Age and Condition
Lenders want to know your car holds its value. Most prefer vehicles that are less than 10 to 15 years old. The car should be in good working condition with reasonable mileage. A well-maintained vehicle will get you a higher loan amount.
Income Verification
Even though the loan is secured by your car, lenders still want to know you can repay. You will need to show a steady income source. This can be from employment, self-employment, Social Security, or other regular income streams.
Insurance and Registration
You must have active auto insurance and current vehicle registration. This protects both you and the lender. Some lenders may also require a spare set of keys or a GPS tracker, though this is less common today.
Credit Score Considerations
Here is the best part. Many car title loan providers do not run a hard credit check. Your credit score may not matter as much because the loan is backed by your vehicle. This makes bad credit loans through title lenders a real option for many people.
How Much Can You Borrow Against Your Car?
The amount you can borrow depends on several factors. Let us break them down so you have a realistic expectation.
Vehicle Value
This is the biggest factor. A newer, higher-value car will get you a larger loan. A 2023 SUV might qualify for $10,000 or more, while an older compact car might only qualify for $1,500 to $3,000.
Your Equity
Lenders base the loan on your loan-to-value ratio, usually between 25% and 50%. If your car is worth $12,000 and you have no outstanding loan, you might qualify for $3,000 to $6,000.
Your Income
Your ability to repay also plays a role. Lenders want to make sure your monthly payments fit comfortably within your budget. Higher income can sometimes unlock a slightly higher loan amount.
State Regulations
Some states have caps on how much you can borrow or what interest rates lenders can charge. It is important to know your local laws before applying.
Quick Comparison Table
| Vehicle Value | Estimated Loan Range | Typical Term |
|---|---|---|
| $5,000 – $8,000 | $1,250 – $4,000 | 12 – 24 months |
| $8,000 – $15,000 | $2,000 – $7,500 | 12 – 36 months |
| $15,000 – $25,000 | $3,750 – $12,500 | 12 – 36 months |
| $25,000+ | $6,250 – $12,500+ | 12 – 48 months |
Keep in mind these are estimates. Your actual loan amount will depend on the lender, your income, and your specific situation.
Pros and Cons of Taking a Loan Against Your Car
Like any financial product, car title loans come with both advantages and risks. Let us look at both sides honestly.
The Pros
- Keep driving your car — you do not have to surrender your vehicle
- Fast approval — many lenders decide within hours
- Bad credit friendly — credit score is not the main factor
- Simple application — minimal paperwork compared to bank loans
- Flexible use of funds — no restrictions on how you spend the money
- No early repayment penalties — many lenders let you pay off early
The Cons
- Higher interest rates — title loans often carry APRs between 15% and 30%
- Short repayment terms — you may need to repay within 12 to 36 months
- Risk of repossession — if you default, the lender can take your car
- Fees — some lenders charge origination fees, late fees, or prepayment fees
- Debt cycle risk — rolling over the loan can lead to mounting costs
Expert Insight
Financial advisors often warn that title loans should be used for short-term needs, not long-term borrowing. If you can repay within a few months, a car title loan can be a helpful tool. But if you stretch the repayment over many months, the interest can add up quickly. Always borrow only what you can comfortably repay.
Common Mistakes to Avoid
Here are some pitfalls that borrowers often fall into:
- Borrowing more than you need — just because you qualify for a higher amount does not mean you should take it
- Not reading the fine print — always review the full loan agreement before signing
- Ignoring the APR — focus on the annual percentage rate, not just the monthly payment
- Choosing the first lender you find — shop around and compare at least three offers
- Forgetting to budget for repayment — make sure the monthly payment fits your cash flow
Tips to Get the Best Loan Against Your Car
Follow these practical tips to make sure you get a fair deal on your vehicle equity loan.
1. Know Your Car’s Exact Value
Do not guess. Get a professional appraisal or use multiple online tools to estimate your car’s worth. The more accurate your valuation, the better offer you can negotiate.
2. Shop Around With Multiple Lenders
Compare at least three lenders before committing. Look at interest rates, fees, repayment terms, and customer reviews. Online comparison platforms can make this process quick and easy.
3. Read the Loan Agreement Carefully
Pay attention to the interest rate, any hidden fees, and the repayment schedule. Ask questions if anything is unclear. A trustworthy lender will explain everything in plain language.
4. Borrow Only What You Need
It can be tempting to take the maximum loan amount. Resist that urge. The less you borrow, the less you pay in interest, and the faster you become debt-free.
5. Set Up Automatic Payments
Avoid late fees and protect your car by setting up automatic payments. Most lenders offer this option and it ensures you never miss a due date.
6. Have a Repayment Plan
Before you sign anything, map out your repayment plan. Know exactly how much you will pay each month and for how long. This keeps you on track and avoids the risk of default.
Quick Tips Box
- Tip: Always check for hidden fees before signing the loan agreement.
- Tip: Choose a lender that reports on-time payments to credit bureaus — this can boost your credit score.
- Tip: If you can make extra payments, do so. This reduces the total interest you pay.
- Tip: Keep your car well-maintained. A higher vehicle value means a better loan offer.
Common Mistakes Section
Let us revisit the most common mistakes people make when taking a loan against their car:
- Not comparing lenders: This can cost you hundreds or even thousands of dollars in extra interest
- Ignoring the total cost: Focus on the full cost of the loan, not just the monthly payment
- Taking a loan you cannot afford: Be honest about your budget and do not stretch yourself too thin
- Rolling over the loan: Extending the term sounds helpful but adds more interest and fees
Expert Insights on Vehicle Equity Loans
According to financial experts, car title loans work best when used as a short-term bridge. If you expect a large payment coming in — like a tax refund or a bonus — a title loan can help you cover expenses until then. The key is to have a clear plan for repayment.
Experts also recommend checking your state’s regulations before applying. Some states have strict caps on interest rates and loan amounts, while others are more lenient. Knowing the rules protects you from predatory lending practices.
Frequently Asked Questions
Can I Take a Loan Against My Car and Keep Driving?
Yes, absolutely. In most cases, you can take a car title loan and continue driving your vehicle. The lender holds your title as collateral, but you keep possession of the car. Once you repay the loan in full, you get your title back. This is one of the main reasons people choose this type of loan.
What Is the Typical Interest Rate for a Loan Against My Car?
Interest rates for auto equity loans typically range from 15% to 30% APR, depending on the lender, your state, and your financial situation. The loan term also affects the rate. Shorter terms usually come with lower rates. Always compare offers from multiple lenders to find the most competitive rate.
Can I Get a Loan Against My Car With Bad Credit?
Yes. Because a title loan is a secured loan backed by your vehicle, many lenders do not require a high credit score. Your car’s value and your ability to repay are the primary factors. This makes it a viable option for people with poor credit or no credit history at all.
How Long Does It Take to Get Approved?
Many lenders offer same day funding. The application process is quick — often under 30 minutes. If you have all your documents ready, you could receive your funds within hours. However, processing times vary by lender and state.
What Happens If I Cannot Repay the Loan?
If you default on the loan, the lender has the right to repossess your vehicle. This is why it is crucial to only borrow what you can afford. Some lenders offer a grace period or loan rollover options, but these usually come with additional fees and higher interest costs. Always communicate with your lender if you are struggling to make payments.
Is a Loan Against My Car the Same as Pawning My Car?
No, they are very different. When you pawn your car, you hand it over to the lender, and they store it. You cannot drive it. With a car title loan, you keep driving your vehicle. The lender only holds the title document. This distinction is important and makes title loans a more practical option for many people.
Conclusion
So, can you take a loan against your car and keep driving? The answer is a clear yes. A car title loan offers a fast, accessible way to get cash when you need it most, without giving up your vehicle. Whether you face an emergency expense, a home repair, or a temporary cash flow gap, this type of loan can provide the relief you need.
But knowledge is power. Now that you understand how vehicle equity loans work, what the requirements are, and the pros and cons involved, you can make a confident decision. Remember to compare lenders, read the fine print, borrow only what you need, and have a solid repayment plan in place.
Taking a loan against your car can be a smart financial move when done right. Use the tips and insights from this guide to navigate the process with ease. Your car is a valuable asset — and now you know how to unlock its value without losing the ability to drive.