Does Car Insurance Cover Accidents on Private Property
Car insurance can cover accidents on private property, but it depends on your policy type, the details of the incident, and who was at fault. Liability coverage typically handles property damage you cause to others, while collision coverage may pay for your own vehicle. Understanding your auto insurance policy is essential before an accident happens on a private driveway, parking lot, or garage.
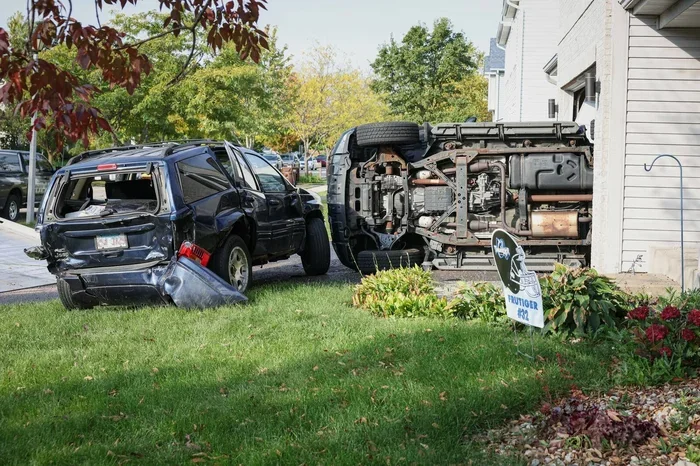
Most drivers assume that car insurance only applies when you are on a public road or highway. But what happens when an accident occurs on private property? Maybe you backed into a fence in your own driveway. Perhaps you scraped a wall in a private parking garage. Or you accidentally damaged a neighbor’s fence while pulling out of their driveway.
The truth is that car insurance covers accidents on private property in many situations. However, the type of coverage you have, the details of the incident, and your state’s laws all play a role in whether your claim will be paid. Understanding how private property accidents are handled can save you from unexpected out-of-pocket costs and a lot of stress.
This guide breaks down everything you need to know about auto insurance coverage for private property accidents. We will walk through the types of coverage that apply, what to do after an incident, and how to avoid common mistakes. By the end, you will have a clear picture of your rights and responsibilities.
Key Takeaways
- Liability coverage usually pays for damage you cause to another person’s property on private land.
- Collision insurance can cover your own vehicle, even if the accident occurs on private property.
- Comprehensive coverage may apply in certain scenarios like theft or weather damage on private property.
- Filing a claim works similarly whether the accident happens on a public road or private property.
- Your insurance rates may increase after a private property accident, just like any other at-fault claim.
- State laws and your specific insurance policy determine what is and isn’t covered.
- Documenting the scene and gathering evidence is critical regardless of where the accident takes place.
📑 Table of Contents
- What Counts as Private Property in an Insurance Context?
- Types of Coverage That Apply to Private Property Accidents
- Does Car Insurance Cover Accidents on Private Property?
- How to File a Claim for a Private Property Accident
- Will Your Insurance Rates Go Up After a Private Property Accident?
- Common Mistakes to Avoid After a Private Property Accident
- How to Determine the Actual Cash Value of Your Vehicle After an Accident
- State Requirements and How They Affect Private Property Claims
- Expert Tips for Protecting Yourself on Private Property
- When to Hire a Lawyer After a Private Property Accident
- Conclusion
What Counts as Private Property in an Insurance Context?
When we talk about private property in the context of car insurance, we mean any location that is not a public road or street. This includes driveways, garages, parking lots owned by businesses or individuals, and private residential streets. Even your own property counts as private property in insurance terms.
Common Private Property Accident Locations
- Home driveways: Backing into a mailbox, hitting a tree, or damaging a garage door.
- Private parking garages: Scraping walls, hitting pillars, or denting another vehicle.
- Apartment complex lots: These are often private property even though they feel like public spaces.
- Friend’s or family member’s property: Accidents that happen when you are visiting someone.
- Workplace parking lots: If your employer owns the lot, it is typically private property.
The key takeaway is that where the accident happens does not automatically disqualify you from coverage. Your insurance policy follows your vehicle, not the location. That said, the specifics of your policy determine what gets paid and how much.
Types of Coverage That Apply to Private Property Accidents
Not all car insurance policies are the same. Different types of coverage respond to different kinds of accidents. Here is a breakdown of the main coverage types that may apply when an accident occurs on private property.
Liability Coverage
Liability coverage is the most basic and essential part of any auto insurance policy. It pays for damage you cause to other people’s property or bodies. If you accidentally hit your neighbor’s fence while pulling out of your driveway, liability coverage would typically pay for the repair costs.
Liability coverage is split into two parts:
- Property Damage Liability (PDL): This pays for damage you cause to another person’s property. For example, if you back into their car in their driveway, PDL covers the repair costs up to your policy limit.
- Bodily Injury Liability: This covers injuries you cause to other people. While less common on private property, it still applies if someone gets hurt in an accident you caused on their property.
Most states require you to carry a minimum amount of liability coverage. You can check your specific state requirements by visiting your insurance provider or your state’s department of motor vehicles.
Collision Coverage
Collision insurance pays for damage to your own vehicle, regardless of who is at fault. This is especially important for private property accidents. If you hit a pole in a private parking lot and damage your bumper, collision coverage would pay for the repairs after you pay your deductible.
One thing to keep in mind: collision coverage is optional in most states. If you have an older vehicle, you might consider whether carrying collision is worth it. To help you decide, you can check what collision insurance costs and whether it makes sense for your situation.
Comprehensive Coverage
Comprehensive coverage covers damage that is not caused by a collision. This includes theft, vandalism, fire, falling objects, and weather damage. If your car gets damaged on private property by a falling tree branch or a hailstorm, comprehensive coverage would apply.
Comprehensive coverage is also optional. It is often paired with collision coverage as part of a full-coverage policy.
Uninsured Motorist Coverage
If someone hits your car on private property and they do not have insurance, uninsured motorist coverage can step in to pay for your damages. This is particularly relevant in parking lots or private garages where hit-and-run incidents can occur.
Does Car Insurance Cover Accidents on Private Property?
The short answer is yes, in most cases. But the long answer depends on several factors. Let us walk through the most common scenarios and how insurance handles each one.
Scenario 1: You Damage Your Own Property
Imagine you are backing out of your driveway and you dent your own garage door. Your collision coverage would pay for your car’s damage. But what about the garage door? In most cases, your property damage would not be covered under your auto policy. You would need to file a claim under your homeowners insurance instead.
This is an important distinction. Your auto insurance covers damage you cause to other people’s property and vehicles. It does not typically cover your own property.
Scenario 2: You Damage Someone Else’s Property
This is where liability coverage shines. If you accidentally hit your neighbor’s car while it is parked in their driveway, your property damage liability coverage would pay for their repairs. You would be responsible for your deductible if you file a collision claim on your own car, but their repairs come from your liability coverage.
Keep in mind that every insurance policy has coverage limits. If the damage exceeds your limit, you would need to pay the difference out of pocket.
Scenario 3: Someone Else Damages Your Car on Their Property
If a friend or family member hits your car while on their own property, their liability coverage should cover your vehicle’s repairs. If they do not have insurance, your uninsured motorist coverage or collision coverage can step in.
Scenario 4: Vandalism or Theft on Private Property
If your car is vandalized or stolen from a private parking lot, comprehensive coverage would cover the damages. This is another reason why having full coverage is valuable, even for accidents that happen off public roads.
How to File a Claim for a Private Property Accident
Filing a claim for an accident on private property follows a similar process to any other accident. The steps you take immediately after the incident can significantly impact the outcome of your claim.
Step-by-Step Claim Filing Process
- Check for injuries: Make sure everyone involved is safe. Call 911 if anyone is hurt.
- Move to a safe location: If the vehicles are drivable, move them out of traffic if possible.
- Document the scene: Take photos from multiple angles. Capture damage to all vehicles and any property damage.
- Exchange information: Get the other driver’s name, contact details, insurance information, and license plate number.
- Gather witness statements: If anyone saw the accident, get their contact information and a brief description of what happened.
- Notify your insurance company: Report the accident as soon as possible. Most companies have apps or online portals for quick reporting.
- File your claim: Submit all documentation, photos, and information through your insurer’s claim system.
- Follow up: Stay in contact with your claims adjuster and provide any additional information they request.
What to Do Immediately After the Accident
Your actions right after the accident matter a lot. Here are some quick tips:
- Do not leave the scene, even if the property is private.
- Do not admit fault at the scene. Let the insurance companies determine who is at fault.
- Do not make verbal agreements with the other party without involving insurance.
- Do take detailed notes about the location, conditions, and circumstances.
For more details on the claims process and what your insurance covers, you can read our guide on does car insurance cover repairs to understand the full scope of coverage.
Will Your Insurance Rates Go Up After a Private Property Accident?
One of the biggest concerns drivers have is whether their insurance rates will increase after a private property accident. The answer is: it depends.
If you are found at fault in the accident, your rates will likely increase at your next renewal. This is true whether the accident happened on a public street or a private driveway. Insurance companies view at-fault accidents as an indicator of higher risk.
However, there are situations where your rates may not increase:
- Not-at-fault accidents: If the other driver caused the accident, their insurance pays, and your rates typically stay the same.
- Accident forgiveness programs: Some insurers offer accident forgiveness for long-term policyholders.
- Comprehensive claims: Vandalism or theft claims on your own vehicle often do not affect your rates the same way at-fault collisions do.
The impact on your rates also depends on your overall driving history and the severity of the damage. A minor scratch in a parking lot is less likely to cause a significant rate increase than a major collision in a private garage.
Common Mistakes to Avoid After a Private Property Accident
Private property accidents can be confusing, and it is easy to make mistakes that hurt your claim. Here are some common errors to avoid:
Assuming Your Policy Does Not Cover Private Property
Many drivers mistakenly believe that because the accident was not on a public road, their insurance will not apply. This is not true. Your auto insurance policy covers your vehicle and your liability virtually anywhere. Do not skip filing a claim just because the accident happened on private property.
Failing to Report the Accident
Some people think that if the damage is minor, they do not need to report it. This is a risky move. Even small damages can worsen over time, and failing to report an accident can give your insurer grounds to deny a later claim. Always report the incident, no matter how minor it seems.
Not Getting Proof of the Other Party’s Insurance
If another vehicle or property is involved, make sure you get their insurance information. Without it, you may have to rely on your own coverage, which could lead to a higher deductible or increased rates.
Skipping Photos and Documentation
Evidence is everything in insurance claims. Without photos, witness statements, and detailed notes, your claim could be delayed or denied. Always document the scene thoroughly before anything is moved or repaired.
How to Determine the Actual Cash Value of Your Vehicle After an Accident
When your vehicle is damaged in a private property accident, your insurer will determine how much they will pay. This is often based on the actual cash value of your car, which accounts for depreciation. If you want to understand how this value is calculated and what it means for your claim, check out our detailed guide on how to determine the actual cash value of a car.
Understanding actual cash value helps you know whether a total loss payout or a repair payout makes more sense for your situation. It is especially relevant for older vehicles where the repair cost might exceed the car’s value.
State Requirements and How They Affect Private Property Claims
Car insurance requirements vary by state. While most states mandate minimum liability coverage, the specific limits and additional coverage requirements differ. For example, if you live in Virginia, you can review the specific insurance requirements for your state through our do you need car insurance in Virginia guide.
Your state’s laws also influence how fault is determined in private property accidents. Some states follow a no-fault system, while others use a traditional at-fault system. Understanding your state’s approach can help you navigate the claims process more effectively.
Key State-Level Considerations
- No-fault states: Each driver’s insurance pays for their own injuries, regardless of who caused the accident.
- At-fault states: The driver who caused the accident is responsible for all damages and injuries.
- Tort states: Injured parties can sue for damages beyond what insurance covers.
- Mandatory coverage minimums: Every state sets a floor for the minimum amount of insurance you must carry.
These state-level differences can significantly impact how a private property accident claim is handled. Always check your state’s specific requirements and how they apply to your situation.
Expert Tips for Protecting Yourself on Private Property
Prevention is always better than dealing with a claim after the fact. Here are some expert-backed tips to help you avoid accidents on private property:
- Install a backup camera: Many private property accidents happen while reversing. A backup camera can prevent collisions with fences, walls, and other vehicles.
- Use your mirrors and turn your head: Do not rely solely on cameras or sensors. Physical head checks are still essential.
- Park in well-lit areas: This reduces the risk of vandalism and makes it easier to see obstacles.
- Know your property boundaries: Be aware of where your property ends and where others begin, especially in tight parking situations.
- Review your insurance policy regularly: Make sure your coverage limits are adequate and that you understand what is and isn’t covered.
For more practical advice on avoiding common pitfalls, consider reading our article on how to avoid car salesman tricks, which covers important tips for making smart decisions about your vehicle and insurance.
When to Hire a Lawyer After a Private Property Accident
Most private property accidents are handled smoothly through insurance claims. However, there are situations where hiring a lawyer makes sense:
- The other driver disputes fault and refuses to cooperate.
- The damage costs exceed your insurance policy limits.
- Someone was injured in the accident.
- Your insurance company denies your claim unfairly.
- The accident involves a complex property dispute.
A lawyer who specializes in auto insurance or personal injury can help you navigate these complicated situations and protect your rights. Many offer free consultations, so it is worth reaching out if you are unsure whether you need legal representation.
Conclusion
Car insurance does cover accidents on private property in most cases. Whether it is liability coverage for damage you cause to others or collision coverage for your own vehicle, your auto policy provides protection regardless of where the accident happens. The key is understanding what your specific policy covers and taking the right steps after an incident.
Always document the scene, report the accident promptly, and know your coverage limits. Avoid common mistakes like assuming private property means no coverage or failing to gather information from the other party. With the right knowledge and preparation, you can handle any private property accident confidently and ensure your claim is processed smoothly.
Review your insurance policy regularly, ask your agent questions, and stay informed about your coverage. Being proactive today can save you significant time, money, and stress tomorrow.
Frequently Asked Questions
Does car insurance cover accidents that happen in my own driveway?
Yes, your car insurance can cover accidents in your own driveway. If you damage another person’s property or vehicle, your liability coverage pays for their repairs. If your own car is damaged, collision coverage applies. However, damage to your own property (like a garage door) is typically not covered by auto insurance and would fall under your homeowners policy instead.
Will my insurance cover damage I caused to a fence on private property?
Yes, if you accidentally hit and damage a fence on private property, your property damage liability coverage will typically pay for the repairs. This applies whether the fence belongs to a neighbor, a business, or any other private property owner. Make sure to report the incident and provide accurate details to your insurer.
Is a parking lot on private property covered by my car insurance?
Absolutely. Private parking lots, including those at shopping centers, apartment complexes, and workplaces, are covered under your standard auto insurance policy. Whether you hit another vehicle, a pole, or a building, your coverage applies the same way it would on a public road.
What happens if the other driver does not have insurance after a private property accident?
If the other driver is uninsured, your uninsured motorist coverage or collision coverage can cover your damages. If you do not have these coverages, you may need to pursue the other driver personally for compensation. This is why carrying uninsured motorist coverage is highly recommended.
Does filing a claim for a private property accident affect my insurance rates?
It can. If you are found at fault in the accident, your rates may increase at your next renewal. However, not-at-fault claims, comprehensive claims, and accidents under your accident forgiveness program may not impact your rates. The severity of the damage and your driving history also play a role.
Can I file a claim if the accident happened on a friend’s private property?
Yes, you can file a claim if the accident occurred on a friend’s property. Your auto insurance covers you regardless of the location. If you damaged their property or vehicle, your liability coverage applies. If your own car was damaged, collision or comprehensive coverage would apply depending on the circumstances.